



From Tenant Damage to Legal Claims: Why HMO Landlord Insurance Matters
Letting out a house in multiple occupation (HMO) brings more moving parts than a standard rental. From shared kitchens to multiple tenancy…

Specialist cover for houses in multiple occupation, built around licensing duties, shared facilities and higher tenant turnover.
Specialist cover for houses in multiple occupation, built around licensing duties, shared facilities and higher tenant turnover.
 Communal areasRent across every roomShared furnishings
 Compare from 20+ Trusted Insurers

Speak to a specialist 0330 027 0996
HMO insurance is landlord cover for a house in multiple occupation, a property let to tenants from more than one household who share facilities. Standard landlord policies often exclude HMOs, so it needs to be arranged specifically.
Any HMO with five or more occupiers from two or more households sharing a kitchen or bathroom requires a mandatory licence. Operating an unlicensed licensable HMO is a criminal offence.
The right HMO cover depends on:
 Number of tenants and householdsWhether the property is licensableTenant type, students, professionals, LHAFurnishings you provideRental income across roomsNumber of HMOs let
Is HMO insurance right for your property?
Is HMO insurance right for your property?
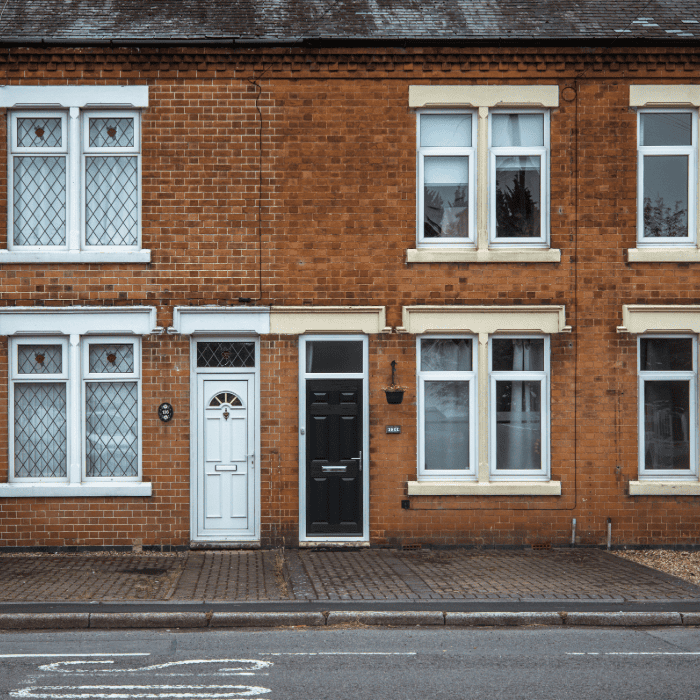
If your property is let to tenants from more than one household who share facilities, it’s an HMO, whether it’s a student house, a professional share or bedsits.
If your property is let to tenants from more than one household who share facilities, it’s an HMO, whether it’s a student house, a professional share or bedsits.
Shared Houses
Professionals or sharers on a joint or individual tenancy agreements.
Student HMOs
Properties let to students, with high turnover and long void periods.
Bedsit HMOs
Individual rooms let separately with shared kitchen or bathroom facilities.
Licensable HMOs
Five or more occupiers from two or more households sharing amenities.
Flats Above Shops
Section 257 and self-contained flats that still meet the HMO definition.
HMO Portfolios
Landlords letting several HMOs under one policy.
What could put your HMO at risk?
What could put your HMO at risk?
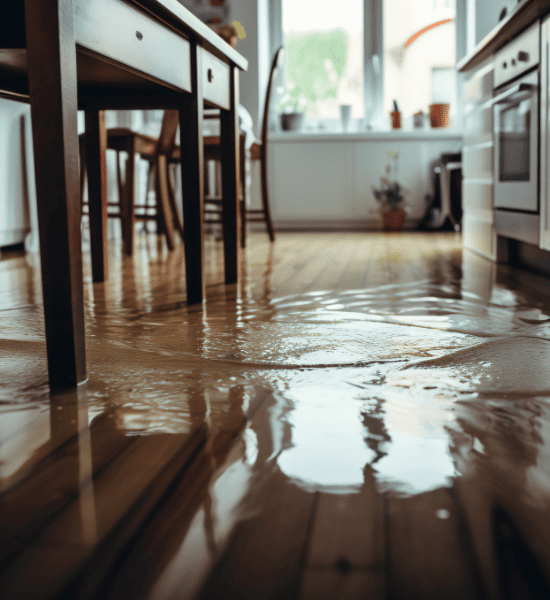
Fire and escape of water dominate HMO claims, and both are more likely where several households cook and wash independently under one roof.
Fire and escape of water dominate HMO claims, and both are more likely where several households cook and wash independently under one roof.
How could a claim affect your property?
How could a claim affect your property?
In an HMO a single incident can stop income from every room at once. Here are four common scenarios and the cover that responds to each.
In an HMO a single incident can stop income from every room at once. Here are four common scenarios and the cover that responds to each.
Fire
A kitchen fire makes the whole house unlettable, not just one room.
What cover may respond?
Buildings + Loss of Rent
Escape of Water
A leak damages several rooms and tenants have to move out.
What cover may respond?
Buildings + Property Owners’ Liability

Storm Damage
Storm damage leaves rooms unusable while repairs are carried out.
What cover may respond?
Buildings + Loss of Rent

Visitor Injury
A tenant is injured on a shared staircase.
What cover may respond?
Property Owners’ Liability
If your property is let to tenants from more than one household who share a kitchen or bathroom, it’s an HMO, and most standard landlord policies won’t cover it.
This cover may be suitable for:
Landlords letting shared housesStudent HMO landlordsOwners of bedsit propertiesOwners letting rooms individuallyLandlords with several HMOsOwners of flats above shopsCover built around your HMO
Cover built around your HMO
Most HMO landlords combine buildings cover with property owners’ liability for communal areas, then add loss of rent across multiple rooms and contents for shared furnishings.
Most HMO landlords combine buildings cover with property owners’ liability for communal areas, then add loss of rent across multiple rooms and contents for shared furnishings.
Buildings Insurance
Protection for the structure, communal areas and permanent fittings, set to full rebuild cost.
Property Owners’ Liability
Protection if a tenant or visitor is injured in a shared hallway, stairwell or kitchen.
Loss of Rent
Helps replace income from every room if the property becomes unlettable, not just one tenancy.
Landlord Contents
Cover for shared furnishings, white goods and appliances across communal areas and rooms.
Rent Guarantee
Covers unpaid rent where one tenant defaults but the rest of the house continues.
Legal Expenses
Legal protection for tenancy disputes, possession claims and licensing matters.
How the quote process works
How the quote process works
Simple steps. Expert advice on the cover your HMO actually needs.
Simple steps. Expert advice on the cover your HMO actually needs.

Tell us about your HMO
Tenant numbers, households, and whether it’s licensable.

Set your rebuild cost
Cover should reflect rebuild cost, not market value.

We compare specialist insurers
We search insurers who actively underwrite HMOs.

Get covered and get your documents
Receive your policy documents, usually the same day.
 UK-based specialist advisersAccess to specialist insurersNo obligation, just expert help
Trusted by thousands of businesses across the UK
Trusted by thousands of businesses across the UK
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
HMO insurance guides
HMO insurance guides
Practical advice on licensing, fire safety and protecting rental income.
Practical advice on licensing, fire safety and protecting rental income.
From Tenant Damage to Legal Claims: Why HMO Landlord Insurance Matters
Letting out a house in multiple occupation (HMO) brings more moving parts than a standard rental. From shared kitchens to multiple tenancy…
HMO Landlord Insurance UK: How It Differs from Standard Landlord Cover
Managing a house in multiple occupation (HMO) brings unique risks compared to letting out a single household property. Understanding the key…
HMO vs Standard Buy-to-Let Insurance: Which One Fits Your Rental Property?
Choosing the right cover for a rental property in the UK depends on how that property is let. HMO landlord insurance and standard buy-to-let…
HMO insurance FAQs
HMO insurance FAQs
Straight answers on licensing, cover and cost.
Straight answers on licensing, cover and cost.
HMO insurance is landlord cover for a house in multiple occupation, a property let to tenants from more than one household who share a kitchen or bathroom. Standard landlord policies often exclude HMOs.
Still have questions?
Our advisers are here to help you find the right solution.