



Do You Need Convenience Store Insurance If You Only Sell Newspapers and Snacks?
Running a small newsagent or corner shop that mainly sells newspapers, snacks, and drinks might seem simple. However, even small stores can face…

Cover for cash and takings in the till, in the safe, on the way to the bank, and for staff assaulted in a hold-up, added to your wider business policy.
Cover for cash and takings in the till, in the safe, on the way to the bank, and for staff assaulted in a hold-up, added to your wider business policy.
 Till and safe cashCash in transitHold-up assault cover
 Compare from 20+ Trusted Insurers

Speak to a specialist 0330 027 0996
Money insurance covers loss of cash and takings by theft, with separate limits for money in the till during trading hours, locked in a safe overnight, and being carried to the bank.
Money cover is an add-on, not a standalone policy. It sits within a wider business or shop policy, alongside your stock, contents and liability cover. If you handle cash on the premises or take it to the bank, ask for a business insurance quote and we will include money cover in it.
“Money” means more than notes and coins. Most wordings also include cheques, postal orders, stamps, gift vouchers, card receipts and other negotiable documents you hold on the premises.
Money insurance can include:
 Cash in the tillCash in transit to the bankAssault benefit for staffMoney in a locked safeTakings kept at home overnightCheques and card receipts
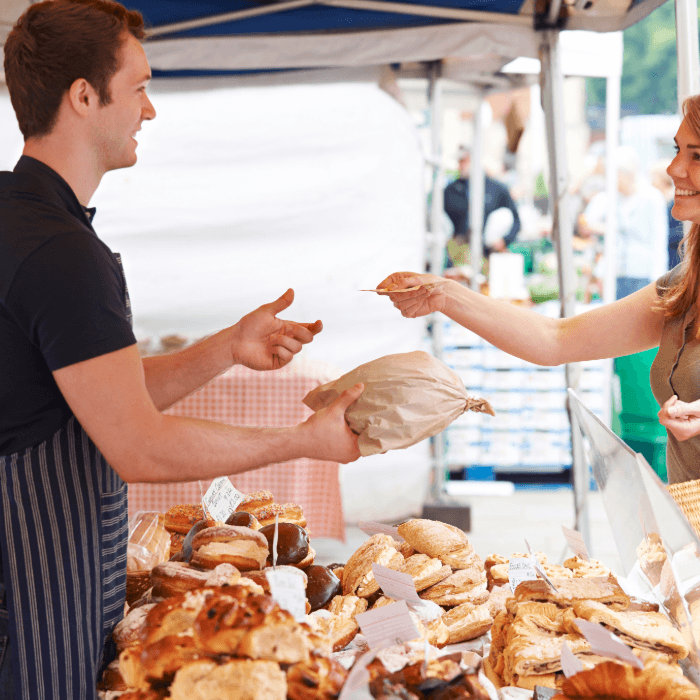
Any business that still takes cash. Card payments have cut the amounts involved, but a convenience store, pub or market stall can hold a day’s takings on site and carry it to the bank by hand.
You should seriously consider cover if you:
Hold a float or changeTrade late at nightKeep takings at home overnightTake cash over a counterBank takings yourselfRun more than one tillLook at the most you ever hold, not the average day. Policies set different limits for each situation, and a claim is paid against the limit that applies where the money was when it went.
The limits are usually modest as standard, so a Saturday night’s takings or a market trader’s float can sit above them without anyone noticing until a claim.
Set a limit for each situation:
In the till during business hoursIn a locked safe outside business hoursIn a private house overnightIn a locked safe in business hoursIn transit to or from the bank
Where money cover applies, and where it doesn’t
Where money cover applies, and where it doesn’t
Money cover follows the cash rather than the building, which is why it is split into limits by situation. Dishonesty by your own staff is a different policy altogether.
Money cover follows the cash rather than the building, which is why it is split into limits by situation. Dishonesty by your own staff is a different policy altogether.
| The loss | Usually insured by | What to know |
|---|---|---|
Till theft in trading hours | Your money policy | Lower limit applies while the till is open |
Safe broken into overnight | Your money policy | Higher limit, but safe specification matters |
Robbery on the way to the bank | Your money policy | Limits often cap the amount per journey |
Money taken by a member of staff | Fidelity guarantee cover | Employee dishonesty needs its own policy |

Top Tip
Vary your banking times and routes, and bank more often rather than letting takings build up. Insurers look at habits as much as amounts, and a predictable Friday run is the one that gets watched.
What could go wrong with your takings?
What could go wrong with your takings?
Most money claims come from a till snatch during trading, a safe attacked after closing, or a hold-up on the way to the bank.
Most money claims come from a till snatch during trading, a safe attacked after closing, or a hold-up on the way to the bank.
Once you’re covered we’ll send your documents the same day. The money section of your schedule is where the limits sit, and they’re worth checking against a real trading day.
If you employ anyone, your employers’ liability certificate must be displayed where staff can see it.
Your schedule typically shows:
Your limit in each situationThe assault benefit amountWho may carry moneyAny safe specification requiredBanking frequency conditions
Cover often bought alongside money insurance
Cover often bought alongside money insurance
Money cover is almost always part of a wider shop or business policy rather than a standalone purchase, sitting next to public liability and cover for your stock and contents.
Money cover is almost always part of a wider shop or business policy rather than a standalone purchase, sitting next to public liability and cover for your stock and contents.
 Recommended
Public Liability
Covers injury or damage claims from customers and visitors.
 Recommended
Business Contents
Covers your tills, safe, fixtures and equipment.
 Optional
Stock Insurance
Covers the goods you hold to sell against theft, fire or damage.
 Optional
Employers’ Liability
A legal requirement once you employ any staff, even casual help.
 Optional
Legal Expenses
Covers legal costs if you end up in a dispute or an investigation.
 Popular
Commercial Combined
Bundle public liability with your other covers into one policy and one renewal date.
There’s no fixed price. The limits you need are the main driver, along with how much cash you hold overnight, the safe you keep it in and how often you bank.
The limits you choose
Each situation carries its own limit, and higher overnight limits cost more.
Claims history
A clean claims record helps keep premiums down at renewal.
How often you bank
Banking daily holds less cash on site than banking once a week.
Your safe
Make, model and whether it’s bolted down all affect what insurers will allow.
Claims history
A clean record keeps your premium down at renewal.
Your trading hours
Late-night trading carries more risk than a nine-to-five counter.
How to get money insurance
How to get money insurance
Getting money insurance takes four steps: tell us how you take payment, set your limits, compare insurers, and get covered, often the same day.
Getting money insurance takes four steps: tell us how you take payment, set your limits, compare insurers, and get covered, often the same day.

Tell us how you take payment
How much cash you handle, when you bank and who carries it.

Set your limits
The most you hold in the till, in the safe and in transit.

We compare specialist insurers
We search our panel of 20+ UK insurers.

Get covered and get your documents
Receive your documents, usually the same day.
 UK-based specialist advisersAccess to specialist insurersNo obligation, just expert help
Trusted by thousands of businesses across the UK
Trusted by thousands of businesses across the UK
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
From everyday business insurance to complex specialist cover, our customers trust Insurance Revolution to find the right protection and provide expert support when it matters.
Money insurance guides
Money insurance guides
Practical advice on limits, safes and banking your takings safely.
Practical advice on limits, safes and banking your takings safely.
Do You Need Convenience Store Insurance If You Only Sell Newspapers and Snacks?
Running a small newsagent or corner shop that mainly sells newspapers, snacks, and drinks might seem simple. However, even small stores can face…
Off‑Licence & Specialty Retail Shop Insurance: What Extra Risks Should You Cover?
Running an off‑licence or specialty retail shop in the UK often brings unique challenges that may not apply to standard retail businesses. Whether…
Shop Equipment & Contents Cover: Avoiding Hidden Risks in Fixtures and Stock
Running a shop in the UK often involves more than protecting the building itself. Many retailers rely heavily on fixtures, fittings, specialist…
Shop Insurance Add‑ons: Legal Expenses & More
Arranging shop insurance in the UK can provide core protection for buildings, contents, and public liability, but many shop owners may benefit from…
What Does Convenience Store Insurance Protect You Against?
Running a corner shop or newsagent can be busy and rewarding. It also comes with risks that could affect your business if something goes wrong.…
Why Newsagents and Corner Shops Need Tailored Insurance
Running a newsagent or corner shop comes with everyday risks. From stock damage to customer injuries, unexpected events can affect both finances and…
Money insurance FAQs
Money insurance FAQs
Straight answers on limits, safes, banking and assault benefit.
Straight answers on limits, safes, banking and assault benefit.
Money insurance covers loss of cash and takings by theft, with separate limits for money in the till during trading hours, locked in a safe, and in transit to or from the bank.
Still have questions?
Our advisers are here to help you find the right solution.